


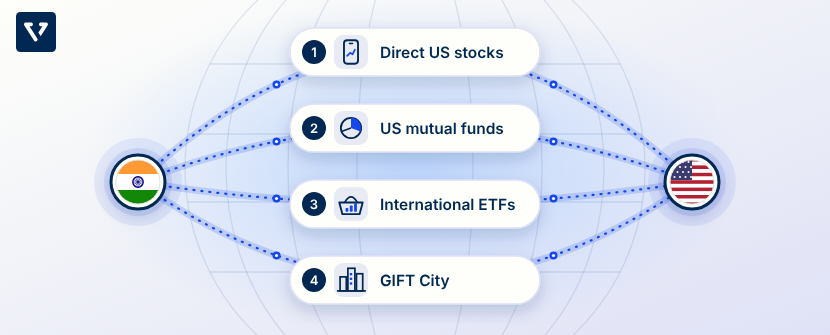
Quick answer: Resident Indians can legally invest in US stocks in four ways. They can (1) open a US brokerage account through a platform like Vested, (2) buy through GIFT City’s NSE IX, (3) invest in Indian international mutual funds, or (4) buy US-focused ETFs listed in India. The first two use the RBI’s Liberalized Remittance Scheme (LRS), which allows up to USD 250,000 per financial year. The last two are bought in rupees but are often closed to new money because of SEBI’s overseas investment cap. Direct investing gives you the widest choice and lets you start with as little as $1.
If you live in India, you have four ways to invest in US stocks. You can open a US brokerage account through a platform like Vested. You can buy through GIFT City. You can invest in an Indian international mutual fund. Or you can buy a US-focused ETF on NSE or BSE. The first two let you invest up to USD 250,000 a year under the RBI’s Liberalised Remittance Scheme. The last two are in rupees, but they are often closed to new money.
Which one makes sense depends on how much control you want and how much you plan to invest. Here’s how they compare.
| Direct (US account) | GIFT City | Intl. mutual funds | India-listed ETFs | |
|---|---|---|---|---|
| You invest in | USD | USD | INR | INR |
| Choice | 10,000+ stocks and ETFs | Smaller, growing list | Few funds, many closed | A handful of ETFs |
| Start from | $1 | Small fractional amounts | ₹100–₹500 SIP (if open) | 1 unit |
| Watch out for | Forex and brokerage costs | Limited stock list | SEBI cap, higher fees | Premium over NAV |
1. Open a US brokerage account (the direct route)
This is the route most people mean when they say they want to buy US stocks. You open an account with a platform like Vested, send money from your bank under LRS, and buy the shares in your own name. You get dividends directly, and you can choose from 10,000+ US stocks and ETFs. That covers everything from Apple to index funds like VOO and QQQ.
The share price doesn’t matter much either. With fractional shares, you can put $10 into a stock that trades at $500, or set up a monthly SIP in an ETF.
Getting started on Vested takes about 10 minutes. Sign up, complete KYC with your PAN and address proof, and transfer funds to your US account. Your bank converts the rupees to dollars and sends them under LRS.
It isn’t free, though. On Vested’s Basic plan, brokerage is 0.25% of the trade value, capped at $35 per trade. Premium costs $4.99 a month and cuts that to 0.15%. Your bank also takes a spread when it converts rupees to dollars, so compare that too. Current fees are on the pricing page.
US markets open at 7 PM IST during US daylight saving time and 8 PM the rest of the year. Here are the full US market timings in India. If you hold RSUs or ESOPs from a US employer, you can also move and diversify them on Vested.
2. Buy through GIFT City
GIFT City is newer. In February 2026, NSE International Exchange (NSE IX) launched its Global Access platform, which lets resident Indians buy US stocks and ETFs, including fractional amounts, through participating brokers. You still send money under LRS, so it counts toward the same $250,000 limit.
The main drawback is choice. The list of available stocks has been much shorter than what you get with a direct US account, though it’s growing. Costs also vary a lot between brokers. GIFT City is also home to some global funds, such as PPFAS’s S&P 500/Nasdaq 100 FoF and the DSP Global Equity Fund.
3. Invest through an international mutual fund
On paper, this is the easiest option. You invest in rupees and run a SIP just like you would in an Indian fund.
The problem is getting in. SEBI caps how much the entire Indian mutual fund industry can invest abroad at USD 7 billion, plus USD 1 billion for overseas ETFs. That limit has been close to full for a while, so fund houses keep pausing new investments or capping SIPs. Several did this again in 2026. (Here’s why the cap exists.)
Fees are also higher. A fund of funds charges its own expense ratio on top of the fees of the US fund it invests in. If you find one that’s open, such as the Motilal Oswal S&P 500 Index Fund, check the subscription status with the AMC before planning a long SIP.
4. Buy a US-focused ETF on NSE or BSE
Some Indian ETFs track the Nasdaq 100 or S&P 500, and you can buy them from your regular demat account. That’s convenient. But the same SEBI cap applies. When fund houses can’t create new units, these ETFs often trade above their real value (NAV), so you can end up overpaying. Check the price against the NAV before you buy.
LRS, TCS and tax: the parts people get wrong
LRS: you can send up to USD 250,000 abroad per financial year, and that covers everything, including travel and education. Budget 2026 didn’t change it. More on how LRS works.
TCS: the first ₹10 lakh you send abroad in a year has no TCS. For investment, anything above that has 20% collected upfront. So if you send ₹15 lakh in a year, ₹1 lakh is held as TCS (20% of the extra ₹5 lakh). You haven’t lost it. You can adjust it against your income tax or get it back as a refund when you file your ITR.
Tax on gains: the US doesn’t tax capital gains for Indian residents, but India does.
| Held for | Tax in India |
|---|---|
| More than 24 months | 12.5% (no indexation), plus surcharge and cess |
| 24 months or less | Your income tax slab rate |
The ₹1.25 lakh exemption you get on Indian shares doesn’t apply here.
Dividends: the US withholds 25% under the India–US tax treaty. You pay tax on the dividend in India at your slab rate, but you can claim credit for the US tax. Under the new Income-tax Act, you claim that credit with Form 44, which replaces Form 67.
Reporting: list your US holdings in Schedule FA every year, even if you didn’t sell anything. Schedule FA follows the calendar year, January to December. Budget 2026 also opened a one-time, six-month window for people to declare foreign assets they had missed reporting earlier.
International mutual funds follow the same 24-month rule: 12.5% after two years, slab rate before that. India-listed ETFs can be different, so check the AMC’s tax reckoner. For the full breakdown, read our guides on tax on US stocks in India and how US dividends are taxed.
So which route should you pick?
If I were starting today, I’d go direct. It’s the only route where I can always invest, choose from the whole US market, and start with a small amount.
For most beginners, a simple first step is a broad index ETF that tracks the S&P 500 or the Nasdaq 100. You can add individual stocks later, once you know the companies better.
Mutual funds still make sense if you only want to invest in rupees and you find one that’s open. If you’d rather have someone else manage it, look at global funds.
You can start investing in US stocks from India on Vested with $1.
Frequently Asked Questions
Is it legal to invest in US stocks from India?
Yes. Resident Indians can invest up to USD 250,000 a year under the RBI’s Liberalised Remittance Scheme.
How much do I need to start?
$1 on Vested, thanks to fractional shares.
Do I pay tax in the US?
Not on capital gains, only in India. US tax is withheld on dividends, but you can claim credit for it in India.
Can I run a SIP in US stocks?
Yes. Vested lets you set up recurring investments in stocks and ETFs.