


Key Takeaways
- Total net sales reached €11.7 billion, up from €9.3 billion in Q2 2026.
- Net income increased to €5 billion from €2.9 billion in the previous quarter.
- Gross margin rose to 57.5% from 54% in Q2.
- ASML sold 121 lithography systems during the quarter, compared with 91 in Q2.
- The company expects Q4 2026 sales of €14.2 billion to €15.2 billion.
- ASML repurchased approximately €4.1 billion worth of shares during Q3.
On October 14, 2026, ASML Holding NV announced Q3 2026 results. The company reported record quarterly sales of €11.7 billion in Q3 2026, along with net income of €5 billion. The Dutch semiconductor equipment maker benefited from high demand for productivity upgrades and continued investment in semiconductor manufacturing, particularly as customers expand their artificial intelligence (AI) capabilities.
The company’s gross margin increased to 57.5%, and earnings per share (EPS) rose to €12.95. ASML also raised its expectations for future equipment demand, noting that planned supply for 2027 and 2028 may not be enough to meet customer requirements.
Source: Press release
ASML Q3 2026 Financial Performance
ASML recorded growth across its key financial measures in the third quarter of 2026. Both revenue and net income increased compared with the previous quarter.
| Financial Metric | Q2 2026 | Q3 2026 |
| Total net sales | €9.33 billion | €11.66 billion |
| Gross profit | €5.04 billion | €6.70 billion |
| Gross margin | 54.0% | 57.5% |
| Net income | €2.92 billion | €4.96 billion |
| Basic EPS | €7.59 | €12.95 |
| Cash and short-term investments | €7.58 billion | €12.74 billion |
Source: ASML’s Q3 2026 financial results. Figures are rounded.
Installed Base Management Sales Support Growth
ASML’s revenue came from two main areas:
- Sales of new semiconductor manufacturing systems
- Services for equipment already installed at customer facilities.
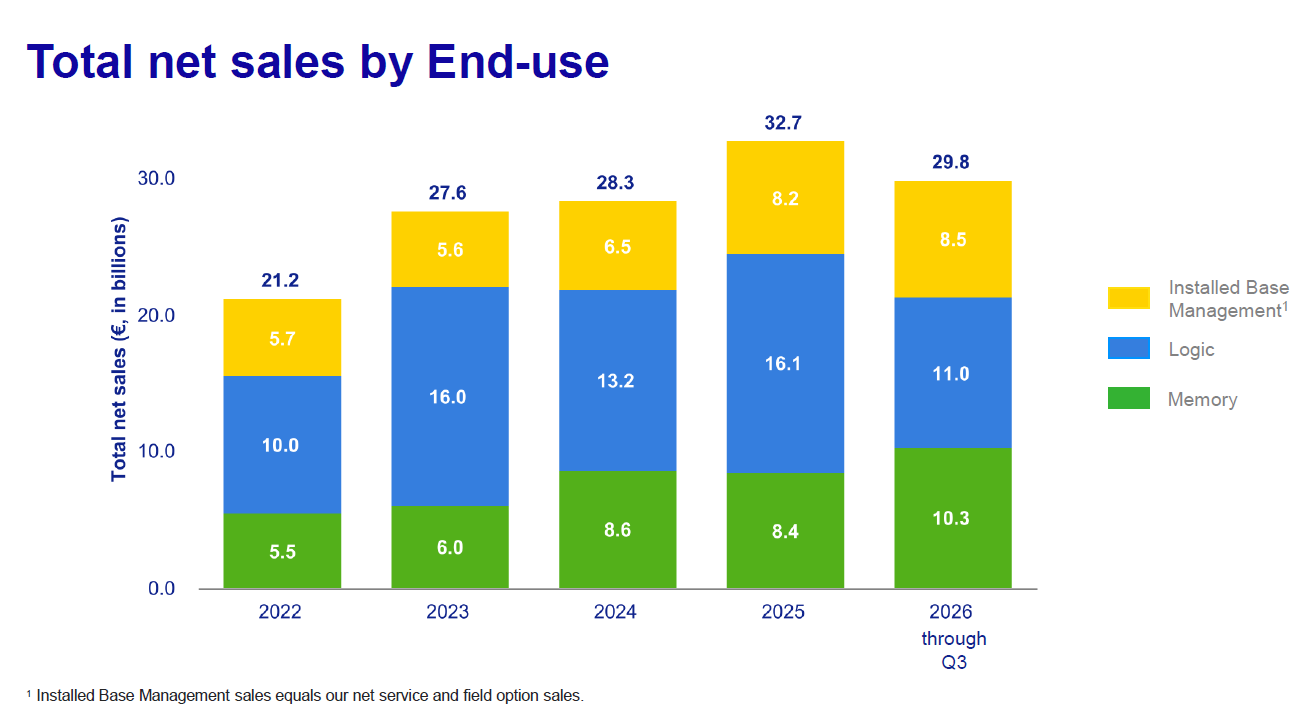
Net system sales reached approximately €8.4 billion in Q3 2026. Installed Base Management sales(services and field options) increased to €3.3 billion from €2.8 billion in Q2.
ASML also sold 121 lithography systems during the quarter, including 113 new systems and eight used systems. This was an increase from the 91 systems sold in Q2.
AI Demand Drives Semiconductor Equipment Outlook
Demand for semiconductor manufacturing equipment remains high as customers plan investments related to artificial intelligence. AI applications need advanced chips and greater computing capacity, increasing the need for sophisticated semiconductor manufacturing technology.
ASML said customers have continued to increase their short- and medium-term equipment demand outlook. Some are also discussing potential orders for the years 2029 and 2030.
The company looks forward to its currently planned supply for the years 2027 and 2028 falling short of customer demand. It is therefore finding ways to increase capacity for 2028 beyond the previously communicated expansion plans.
This demand outlook is important for ASML because its lithography systems play an important role in producing advanced semiconductors. However, the company will need to manage capacity and production carefully to meet customers’ requirements.
ASML Q4 and Full-Year 2026 Outlook
ASML expects its financial performance to strengthen further in the fourth quarter of 2026.
| Financial Metric | Company Guidance |
| Q4 2026 total net sales | €14.2 billion–€15.2 billion |
| Q4 2026 gross margin | Around 57% |
| Full-year 2026 total net sales | €44 billion–€45 billion |
| Full-year 2026 gross margin | Around 56% |
| Q4 research and development costs | Around €1.2 billion |
| Q4 selling, general and administrative costs | Around €0.4 billion |
ASML Announces Share Buybacks and Dividend
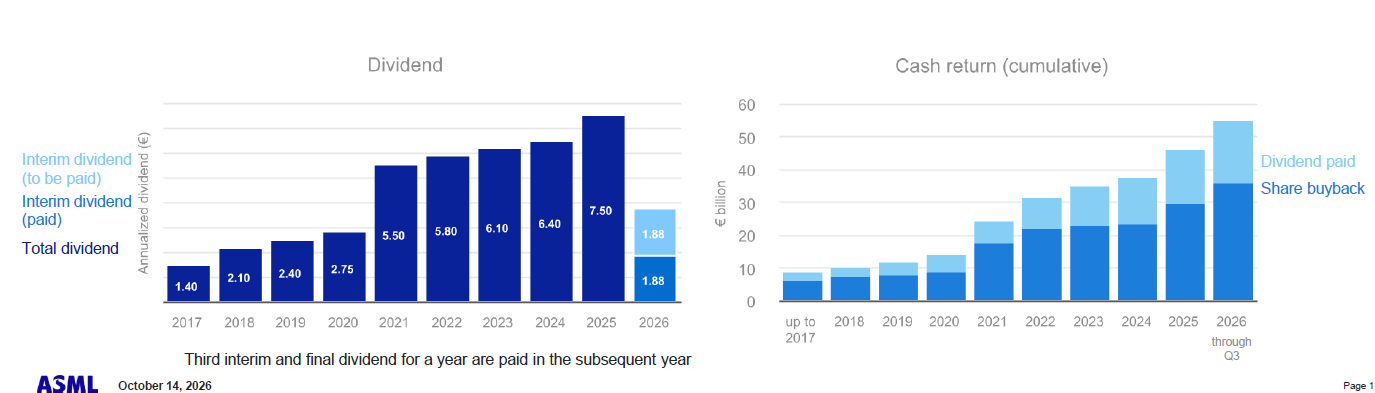
ASML continued to return capital to its shareholders during Q3 2026. Under the 2026–2028 share buyback programme, the company purchased approximately €4.1 billion worth of shares during the quarter.
The company also announced an interim dividend of €1.88 per ordinary share for 2026. The dividend payment is scheduled for November 4, 2026.
Source: Press release
CEO Statement
ASML President and Chief Executive Officer Christophe Fouquet said, “In the third quarter we reported a record total net sales of €11.7 billion, towards the high end of our guidance, reflecting the strong execution of our ramp-up. Installed Base Management sales came in above guidance at €3.3 billion as a result of the continued strong demand for productivity upgrades. This drove the gross margin above guidance at 57.5%.”
He further added, “We expect fourth-quarter 2026 total net sales between €14.2 billion and €15.2 billion, with a gross margin around 57%. We expect R&D costs of around €1.2 billion and SG&A costs of around €0.4 billion. We expect total net sales for 2026 to be between €44 billion and €45 billion, with a gross margin around 56%.”
What Investors Can Take From ASML’s Q3 2026 Results
- Demand is outrunning supply, which supports pricing power and visibility
ASML says its planned 2027 and 2028 supply will not fully meet customer demand. Some customers are already discussing orders for 2029 and 2030. For investors, that means revenue visibility stretches further than usual for a cyclical equipment maker. Interest in future orders is not the same as signed orders, though, and ASML’s own risk disclosures say so.
- The beat came from quality, not just volume
Sales landed at the high end of the €11–12 billion guidance range. Installed Base Management sales of €3.3 billion came in above the roughly €2.9 billion guided, and gross margin of 57.5% beat the 55–57% range. Margin expansion usually matters more to earnings than extra revenue alone.
- Operating leverage is working
Operating margin rose to 44.4% from 37.1% in Q2 and 32.8% a year earlier. Operating costs fell from about 17% of sales to about 13%, so each extra euro of sales is converting to profit at a higher rate.
- Read net income with care
Net income of €4.96 billion includes a €509.7 million gain on equity investments that was not in Q2. Excluding it, and ignoring any tax effect, net income is about €4.5 billion. That is still up roughly 50% on the quarter, but the headline 70% jump overstates the underlying improvement.
- Cash generation and shareholder returns stepped up
Operating cash flow was €11.8 billion. Buybacks were €4.1 billion, up from €1.1 billion in Q2, and dividends paid were €721 million. Together, that is roughly equal to Q3 net income. The weighted share count has fallen from 387.3 million a year ago to 383.1 million.
Risks and watch-points
- Margins: Q4 gross margin is guided to about 57%, slightly below Q3’s 57.5%, even as sales are guided up 22–30% quarter-on-quarter. Capacity expansion costs are the likely factor to watch.
- Execution: Meeting demand depends on supply chain capacity and on delivering systems on time.
- External factors: ASML cites export controls, tariffs, geopolitics and order push-outs or cancellations as risks.
Source: