


Key Takeaways
- Total revenue increased 8% year over year to $23.845 billion in Q3 2026, driven by growth in Services, Wealth, Markets and Banking.
- Net income rose to approximately $5.245 billion from $3.8 billion in the year-ago quarter, supported by higher revenue and the absence of the previous year’s goodwill impairment charge.
- Earnings per diluted share increased to $2.85 from $1.86 a year earlier, reflecting higher net income and a lower share count due to share repurchases.
- Services revenue increased 15% to $6.6 billion, while Wealth revenue rose 15% to $3.3 billion.
- Markets revenue increased 6% to $6.1 billion, while Banking revenue grew 6% to $1.7 billion.
- U.S. Consumer Cards revenue was unchanged at $4.7 billion, while net income declined 8% to $851 million.
On October 13, 2026, Citigroup Inc. (NYSE: C) reported financial results for the third quarter of 2026. The company reported net income of $5.2 billion, or $2.85 per diluted share, compared with $3.8 billion, or $1.86 per diluted share, in the third quarter of 2025. Revenue increased 8% year over year to $23.8 billion.
The bank also returned $4.1 billion to its common shareholders by repurchasing shares and paying dividends during Q3.
Citigroup Q3 2026: Key Financial Highlights
The following table summarises Citigroup’s financial performance in the third quarter of 2026 compared with the same quarter in 2025.
| Financial metric | Q3 2026 | Q3 2025 | YoY change |
| Total revenue | $23.8 billion | $22.1 billion | +8% |
| Net income | $5.2 billion | $3.8 billion | +40% |
| Earnings per share (EPS) | $2.85 | $1.86 | +53% |
| Operating expenses | $14.0 billion | $14.3 billion | -2% |
| Provision for credit losses | $2.6 billion | $2.5 billion | +6% |
| End-of-period loans | $820 billion | $734 billion | +12% |
| End-of-period deposits | $1.5 trillion | $1.4 trillion | +9% |
Note: Figures are rounded.
In Q3 2025, Citigroup recorded a $726 million impairment related to its agreement to sell a 25% stake in Grupo Financiero Banamex.
Excluding this item, net income in the year-ago quarter was $4.5 billion, and EPS was $2.24. On this basis, Q3 2026 net income increased approximately 16%, while EPS rose 27%.
Source: Investing.com
Revenue Growth and Operating Expenses
Citigroup’s revenue increased 8% to $23.8 billion. These gains were partly offset by lower revenue from its All Other category.
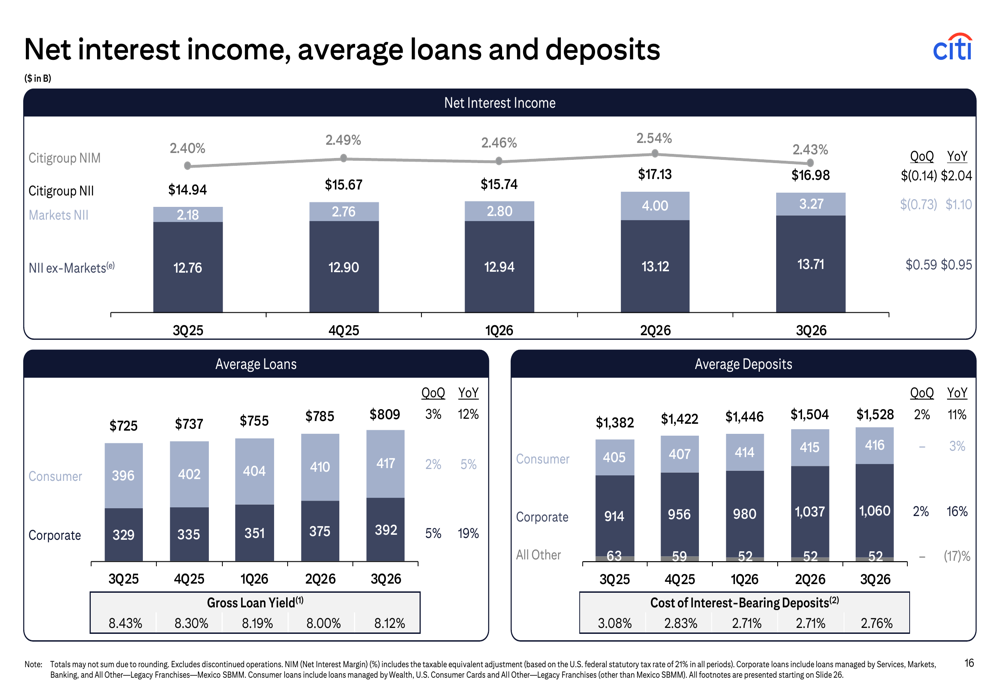
Net interest income rose 14%, and Non-interest revenue declined 4%.
Operating expenses decreased 2% to $14.0 billion. However, compensation, deposit insurance and transaction-related costs increased. Excluding the impairment charge, operating expenses rose 3%.
Credit Losses and Loan Growth
Citigroup’s provision for credit losses increased to $2.6 billion from $2.45 billion in Q3 2025. This included $2.2 billion in net credit losses and a net reserve build of approximately $369 million.
The bank’s total allowance for credit losses stood at $22.4 billion at the end of the quarter, compared with $23.8 billion a year earlier. Non-accrual loans declined 12% to $3.3 billion.
End-of-period loans increased 12% year over year to $820 billion, while average loans rose 12% to $809 billion. End-of-period deposits grew 9% to approximately $1.5 trillion, supported by an increase in Services.
Citigroup’s Business Segment Performance
The following table highlights revenue and net income growth across Citigroup’s major businesses.
| Business segment | Q3 2026 revenue | YoY revenue growth | Q3 2026 net income | YoY net income growth |
| Services | $6.6 billion | +15% | $2.6 billion | +27% |
| Markets | $6.1 billion | +6% | $1.7 billion | +2% |
| Banking | $1.7 billion | +6% | $378 million | +40% |
| Wealth | $3.3 billion | +15% | $585 million | +93% |
| U.S. Consumer Cards | $4.7 billion | 0% | $851 million | -8% |
Note: Figures are rounded. Revenue and net income growth rates are year-over-year.
- Services: Revenue rose 15% to $6.6 billion, driven by growth in Treasury and Trade Solutions and Securities Services.
- Markets: Revenue increased 6% to $6.1 billion, supported by stronger equity and fixed-income trading.
- Banking: Revenue grew 6% to $1.7 billion, led by a 9% increase in investment banking revenue.
- Wealth: Revenue climbed 15% to $3.3 billion, while net income surged 93% to $585 million.
- U.S. Consumer Cards: Revenue remained flat at $4.7 billion, while net income declined 8% to $851 million.
Capital Position and Shareholder Returns
Citigroup’s preliminary Common Equity Tier 1 (CET1) capital ratio stood at 12.8% at the end of Q3 2026, unchanged from the previous quarter. Its supplementary leverage ratio was 5.0%, compared with 5.2% at the end of Q2 2026.
| Capital and shareholder metric | Q3 2026 | YoY change |
| Book value per share | $115.61 | +7% |
| Tangible book value per share | $101.59 | +6% |
| CET1 capital ratio | 12.8% | 0.5 percentage-point decline |
| Share repurchases and dividends | $4.1 billion | — |
The CET1 ratio was down from 13.3% a year earlier. During Q3, Citigroup gave a return of $4.1 billion to common shareholders through share repurchases and dividends. Its reported payout ratio was 85%.
Source:
https://www.citigroup.com/rcs/citigpa/storage/public/Earnings/Q32026/2026prqtr3rslt.pdf