


Key Takeaways
- Revenue increased by 50.9%, and net income surged 68.7% year over year. It is the sixth record profit in a row.
- Both revenue and profit beat the analyst forecasts.
- High-performance computing now makes up 68% of revenue.
- Gross margin decreased to 66.4% from 67.7%.
- TSMC share price fell because of margin and spending worries.
On October 15, 2026, TSMC (TWSE: 2330, NYSE: TSM) announced its Q3 results for the period ended September 30, 2026.
The world’s largest contract chipmaker company reported revenue of NT$1,494.24 billion and net income of NT$763.06 billion. Diluted EPS (earnings per share) is at NT$29.43, equivalent to US$4.60 per ADR unit.
Revenue increased by 50.9% from the last year. Net income and EPS both rose 68.7%. Net income grew 68.7%, and sales grew 50.9%. Each extra dollar of revenue is landing in profit, not getting eaten by costs. It is also the sixth record profit quarter in a row.
TSMC’s management is optimistic about the fourth quarter and raised its full-year growth forecast. Still, the share price slipped after the report.
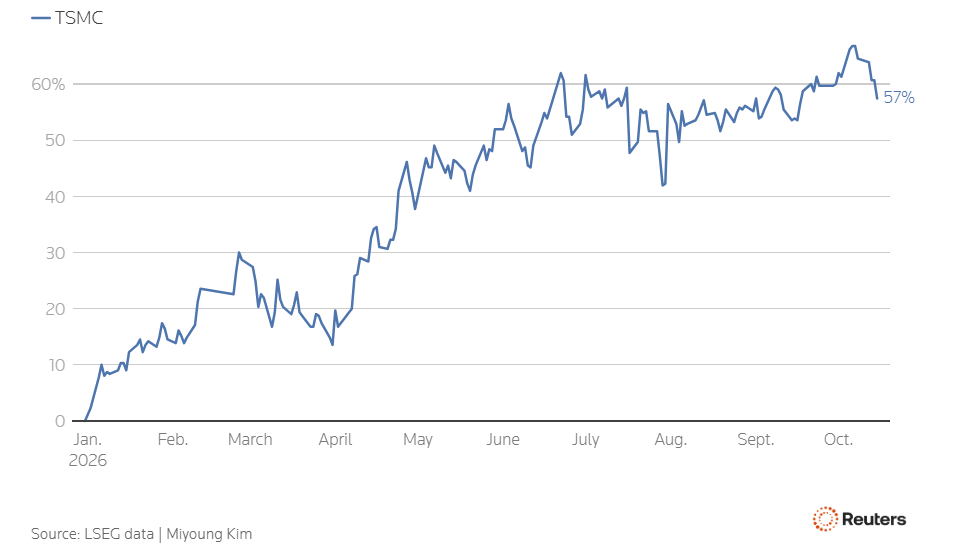
TSMC share price is up nearly 60% so far in 2026, due to growing demand for AI chips.
TSMC’s Q3 2026 Consolidated Results
(NT$ million, except EPS)
| Particulars | Q3 2026 | Q3 2025 | YoY Change (%) | Q2 2026 | QoQ Change (%) |
| Net sales | 1,494,243 | 989,918 | 50.9% | 1,270,381 | 17.6% |
| Gross profit | 992,379 | 588,543 | 68.6% | 860,311 | 15.4% |
| Income from operations | 876,445 | 500,685 | 75.0% | 766,603 | 14.3% |
| Income before tax | 911,039 | 525,369 | 73.4% | 862,430 | 5.6% |
| Net income | 763,064 | 452,302 | 68.7% | 706,562 | 8.0% |
| EPS (NT$) | 29.43 | 17.44 | 68.7% | 27.25 | 8.0% |
Note:
- The Q3 2026 figures are not yet approved by the Board of Directors.
- Q3 2026 EPS is calculated using 25,932 million weighted-average outstanding shares.
- Q3 2025 EPS is calculated using 25,930 million weighted-average outstanding shares.
Profit margins: Strong, but a little lower
TSMC kept its margins very high. Gross margin was 66.4%, operating margin was 58.7%, and net profit margin was 51.1%.
Margins did slip from the second quarter, when gross margin was 67.7% and operating margin was 60.3%. TSMC had given a warning about this. Its own guidance for the quarter was 65% to 67% for gross margin. A quarter that lands inside that range is not a surprise. However, investors watch these numbers closely.
2nm chips enter the mix
TSMC broke down its wafer sales by chip technology for the third quarter:
- 3nm: 33% of wafer revenue
- 5nm: 28%
- 7nm: 10%
- 2nm: 8%
Add those up, and you get 79%. That is the share of wafer revenue from advanced chips, meaning 7nm and smaller, and it is up from 77% in the second quarter.
The number I’d watch is the smallest one. 8% for 2nm doesn’t sound like much, but this is TSMC’s newest technology, and it has just started to scale. New chip technologies usually cost more to make at first, because the factory is still learning how to build them well. That can pull margins down for a few quarters. TSMC says the 2nm ramp will be steep, so the margin effect could show up soon.
What TSMC expects for Q4
CFO Wendell Huang says customers still want TSMC’s most advanced chips, and he expects that to continue. The third quarter showed it, and he thinks the fourth quarter will too. He singled out 2nm, which TSMC plans to ramp up quickly.
TSMC then put numbers on the outlook. It assumes an exchange rate of 31.8 NT dollars to one US dollar and expects:
- Revenue: US 52.3 billion to US 54.3 billion
- Gross margin: 65% to 67%
- Operating margin: 56.5% to 58.5%
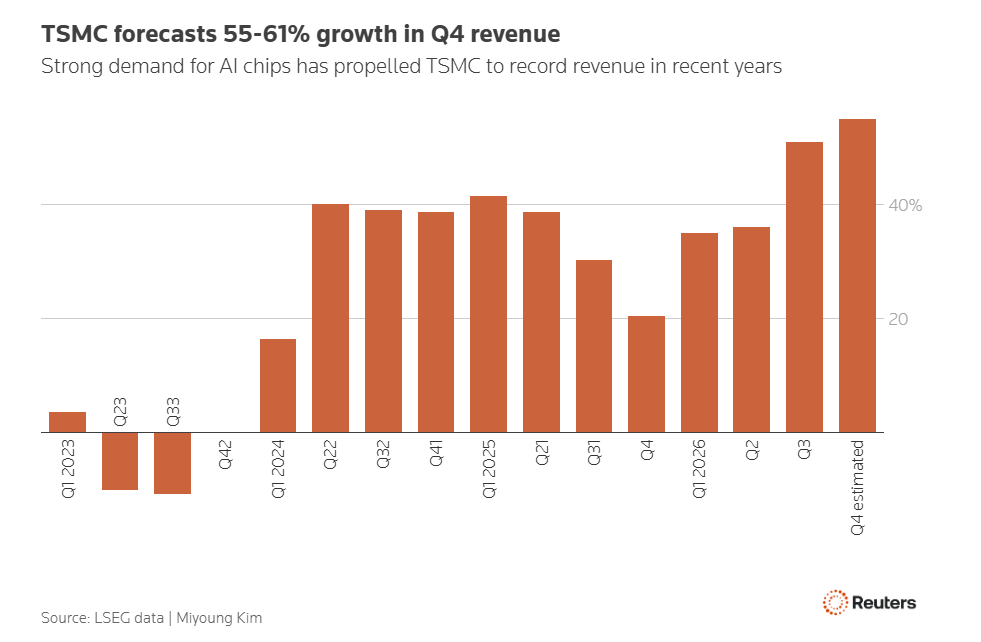
The midpoint of the revenue range is US 53.3 billion. That is about 14% more than the US46.72 billion TSMC earned in the third quarter. So, the company expects growth to keep running fast. It also expects margins to hold steady, even with 2nm production growing. That is a bold promise.
How the results compared with expectations
| Particulars | Expected | Actual | Difference |
| Net profit | NTD 746.3 billion (LSEG SmartEstimate) | NTD 763.06 billion | about +2.2% |
| Revenue | NTD 1.46 trillion (LSEG consensus) | NTD 1.494 trillion | about +2.3% |
| Revenue in USD | USD 44.6-45.8 billion (TSMC guidance) | USD 46.72 billion | about 2% above the top of the range |
| Operating margin | 56%-58% (TSMC guidance) | 58.7% | above the top of the range |
| Gross margin | 65%-67% (TSMC guidance) | 66.4% | above the midpoint |
The profit beat of about 2.2% matched the revenue beat (about 2.3%). It sold more chips than analysts expected.
What the numbers tell us
TSMC’s stock has climbed so far this year that a 2% beat barely counts as news. TSMC posted 51.1%, just above that band. So the market got what it expected, not a disappointment.
What happens next depends on 2nm. If costs fall as production matures, as they did with earlier nodes, margins stay high. If they don’t, this quarter may look like the peak.
Then there is the spending. According to news reports, TSMC is building close to 20 new fabs, most of them in Taiwan. That is a big bet that AI demand will last for years. It is also a big bill. If demand cools, TSMC still has to pay for all that capacity.
Last, TSMC now depends on one customer group more than ever. High-performance computing brings in 68% of revenue, up from 57% a year ago. That works well while AI budgets grow. But if they shrink, TSMC has fewer other businesses to soften the blow.
Source:
https://pr.tsmc.com/english/news/3346